The Invisible Price Tag on Your Agony
Have you ever stared at a lowball settlement offer and felt completely insulted? I almost signed away my rights after a bad crash simply because I was tired of arguing with the insurance adjuster. Let me pull back the curtain on the secret math they use to price your pain, and show you exactly how to fight back for the money you actually deserve.
When the insurance company finally called, I thought they were going to help me. The adjuster sounded so incredibly nice on the phone. They offered to pay all my hospital bills and even threw in a few thousand dollars extra for my "inconvenience."
Because I was desperate and exhausted, I almost said yes right there. I had absolutely no idea that my constant sleepless nights, my intense fear of driving, and the stabbing pain in my back were worth significantly more than what they offered. I didn't know they were secretly using a mathematical formula to slap a cheap price tag on my daily misery.
They look at your medical files, plug some numbers into a computer, and spit out an offer that barely covers your basic rent. They completely ignore the fact that you cannot pick up your child anymore without crying in pain. They do not care that you had to cancel your family vacation because sitting in a plane seat feels like torture.
But you do not have to surrender your rights to these massive companies. There is a very specific, logical method behind their madness. Once you understand exactly how they calculate your misery, you can turn their own secret math formula against them.
Decoding the Insurance Company's Secret Formula
When you get hurt in an accident, your financial losses are basically split into two completely different categories. The first category is incredibly easy to prove. We call these "special damages" or economic damages.
These are the things that have a physical receipt attached to them. Your ambulance bill, your surgery costs, the money you lost because you missed two weeks of work—all of these things have a fixed, undeniable price tag. You just add them up on a calculator.
But how do you put a firm price on the fact that you can no longer sleep through the night without heavy medication? How do you calculate the exact dollar value of missing your daughter's wedding because you were stuck in a hospital bed?
This second category is called "general damages" or non-economic damages. Because human suffering does not come with a printed receipt, the insurance industry had to invent a way to calculate it. They needed a standard system so their adjusters could process thousands of claims very quickly.
To solve this problem, they created a very specific mathematical trick known as the multiplier method. Understanding this single concept is the absolute key to fighting for a fair check.
The Basics of the Multiplier Method
The concept behind the multiplier method is actually quite simple. The insurance adjuster takes the total exact amount of your physical medical bills and multiplies that number by a specific factor. This factor, or multiplier, almost always falls somewhere between 1.5 and 5.
The final number they get from this simple multiplication is what they consider the fair value of your pain and suffering.
Let us look at a very basic, clear example. Imagine you were rear-ended at a stoplight, and you suffered a moderate whiplash injury.
Your total physical medical bills (hospital visit, X-rays, and physical therapy) equal exactly $10,000.
The insurance adjuster reviews your file and decides your injury deserves a multiplier of 2.
They take your $10,000 in medical bills and multiply it by 2.
This equals $20,000.
Therefore, they will offer to pay your $10,000 medical bills, plus an additional $20,000 specifically for your pain and suffering. Your total settlement offer would be $30,000.
Quick Multiplier Reality Check:
-
Soft Tissue Injury (Sprain): $5,000 medical bills x 1.5 = $7,500 pain value.
-
Hard Injury (Broken Bone): $5,000 medical bills x 3.0 = $15,000 pain value.
-
Notice the trick? The exact same medical bill gets doubled just based on the type of injury you suffered.
Pro Tip from My Own Mistakes:
When I got my first settlement offer, I panicked because I had already used my health insurance to pay half my hospital bills. I thought I could only claim the out-of-pocket money I spent. I was completely wrong. When calculating your multiplier, you always use the total, original billed amount from the hospital, regardless of what your private health insurance covered. Do not let the adjuster trick you into lowering your starting number!
Who Actually Chooses the Number?
This is where the entire system becomes highly controversial and deeply unfair to victims. The multiplier is not chosen by a doctor, and it is certainly not chosen by a judge. The specific multiplier applied to your life is chosen entirely by the insurance adjuster handling your file.
These adjusters are heavily trained employees working for a massive corporation. Their primary job is to save their employer money, not to give you a generous gift. They will naturally try to assign the absolute lowest multiplier possible to your claim.
They will try to argue that a 1.5 multiplier is perfectly fair for your broken leg. Your goal is to gather enough hard evidence to force them to use a 3 or a 4.
This creates a massive negotiation battle. You are fighting to prove the severity of your pain, while they are fighting to minimize your experience.
This specific visual breakdown explains exactly how adjusters try to manipulate this number against you during phone calls.
What Makes the Multiplier Go Up or Down?
So, how does an adjuster actually decide if your pain is worth a 1.5 or a solid 5? They look at a highly specific list of variables surrounding your accident. They are basically scoring your misery based on a checklist.
If you want to secure a higher multiplier, you need to understand exactly what evidence triggers a higher score. Let us break down the exact factors that heavily influence their final decision.
1. The True Severity of Your Physical Injuries
Not all injuries are treated equally in the eyes of an insurance company. A simple sprained ankle will almost always receive a very low multiplier, usually around 1.5 or 2. This is because a sprain heals relatively quickly and does not usually leave permanent damage.
However, if you suffer a severe, catastrophic injury, the multiplier naturally climbs. Injuries like shattered bones requiring surgical plates, severe traumatic brain injuries, or deep burns will often trigger a multiplier of 4 or 5. The rule is simple: the more brutal and terrifying the physical injury, the higher the multiplier must be.
2. The Length of Your Medical Recovery
Adjusters look very closely at the timeline of your medical treatment. If you simply visit the emergency room once and never see a doctor again, the adjuster assumes you healed instantly. They will assign a very low multiplier because your suffering was incredibly short.
On the other hand, if you require six continuous months of painful physical therapy just to learn how to walk again, your multiplier increases heavily. A long, well-documented trail of medical appointments proves that your pain disrupted your daily life for a massive amount of time.
3. Permanent Scars and Lifelong Disfigurement
If an accident leaves you with a permanent, visible reminder of the trauma, the insurance company must pay heavily for that reality. Deep, visible scars on your face or arms carry significant weight.
Losing the normal function of a body part also triggers a massive multiplier increase. If a dog bites your hand and leaves you with permanent nerve damage so you can no longer play the piano, your life is forever altered. Permanent damage almost always pushes the multiplier toward the absolute maximum limit.
The Deadly Trap of "Soft Tissue" Injuries
There is one specific type of injury that insurance adjusters absolutely love to fight against. These are commonly known as "soft tissue" injuries. This category includes things like whiplash, strained back muscles, and deep bruising.
Adjusters fight these claims fiercely because soft tissue injuries usually do not show up clearly on standard X-rays. Because the pain is mostly invisible on a medical scan, the adjuster will quickly accuse you of faking or exaggerating your pain to get a bigger check.
If your primary injury is whiplash, the adjuster will almost always start their negotiation with an insulting 1.5 multiplier. They will argue that sore muscles heal quickly and require very little real suffering.
Adjuster's Insider Secret:
Insurance companies actually use computer software (like Colossus) to spit out these multiplier numbers. The software scans your medical records for specific "trigger words." If your doctor writes "severe radiating pain" instead of just "back hurts," the software automatically bumps up your multiplier score!
Myth vs. Reality: The Soft Tissue Struggle
-
The Myth: If my bones are not physically broken, the insurance company will not pay me any money for pain and suffering.
-
The Reality: Soft tissue injuries are incredibly painful and highly compensable. However, you must have incredibly detailed doctor's notes and consistent physical therapy records to force the adjuster to take your invisible pain seriously.
How Your Daily Life Impacts the Calculation
The formula goes far beyond just looking at your hospital chart. A good legal argument forces the adjuster to look at exactly how the injury destroyed your normal daily routine.
Imagine two different people suffer the exact same broken arm in a car crash.
Person A is an accountant who sits at a desk all day. They can still go to work, type with one hand, and generally continue their normal quiet life while the arm heals.
Person B is a professional tennis coach who makes their living entirely through physical movement. They also play on a local softball team every single weekend and have two toddlers they carry around.
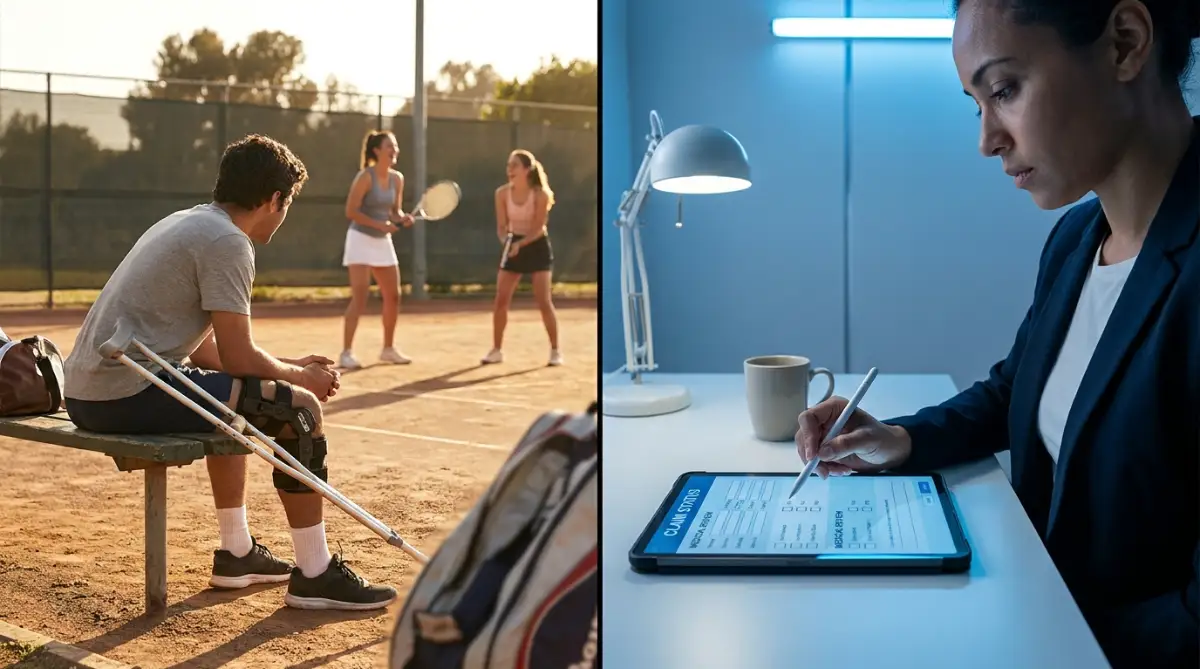
Even though the broken bone is exactly the same, Person B will almost certainly receive a much higher multiplier. The injury completely stopped them from doing their job, ruined their favorite weekend hobby, and heavily impacted their ability to parent.
When you explain your suffering, you cannot just say, "My arm hurts." You must provide highly specific, emotional examples of exactly what the pain stole from your daily life. The more the injury ruined your normal routine, the higher the multiplier should absolutely be.
The "Per Diem" Approach: An Alternative Strategy
While the multiplier method is the most common way insurance adjusters calculate pain and suffering, it is not the only trick they use. Sometimes, especially in cases where your recovery takes several months but your actual medical bills are relatively low, they might switch to the "Per Diem" method.
Per Diem is simply Latin for "per day." Instead of multiplying your total medical bills, the adjuster assigns a specific dollar amount to every single day you lived with the pain. They then multiply that daily rate by the total number of days it took you to fully recover.
Imagine you suffered a badly sprained back that required exactly 100 days of rest and physical therapy before you felt completely normal again. The adjuster might look at your daily salary and decide your pain is worth exactly $150 per day.
They simply multiply 100 days by $150, resulting in a total pain and suffering offer of $15,000.
Th